Wednesday, November 16, 2016

Business Loan - No Real Estate Collateral

to me
South End Capital News
View this email in your browser

Recent Funding

$605,000 Business Loan - No Real Estate Collateral

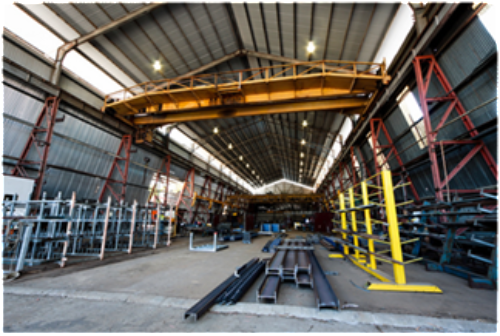
Transaction Overview - Steel Fabrication, Co. 

Earlier in the year this borrower needed $122,100 of quick working capital and didn't have time to wait for an SBA loan. We provided his business working capital in a matter of days, and when he was ready, started him on the SBA takeout loan process.

We consolidated the balance of our private business loan, paid off additional business debt, provided $89,000 of fresh working capital and $370,000 for machinery and equipment. This loan was priced at 6.25% and amortized for 10 years.

SBA Unrestricted Program

SECC offers an aggressive SBA loan program priced at a maximum annual interest rate of 6.25%, amortized over 10 years (25 years, if the business has available real estate collateral). The program features one affordable monthly payment and often no prepayment penalty. SECC can consolidate a business owner’s expensive debt or merchant cash advances, remedy stifling business issues, provide expansion funds and offer unrestricted working capital to assist with new growth and other business needs. SECC imposes few business-type restrictions, will consider borrower credit down to 580 (or lower), can work with past borrower bankruptcies or foreclosures, and will fund from $250,000 to $5,000,000 in all 50 states.

Closing Highlights

Steel Fabrication, Co.

North Carolina

  • No real estate collateral
  • Working capital provided
  • 6.25% rate, 10 yr. term
  • Monthly payment
  • No prepayment penalty
Apply Online

Program Highlights

Program Parameters

Nationwide

  • Financing from $250K to $5MM 
  • Low credit score minimum
  • All industries considered
  • No collateral required
  • Broker rebate available
Email a Scenario
Facebook
Twitter
Website
Email
LinkedIn

About South End Capital

South End Capital Corporation "SECC", founded in February of 2009, is a nationwide, non-conforming lender (CA Finance Lenders License # 603 L334) providing collateralized and uncollateralized loans to business owners and real estate investors directly, and in participation with third-party lenders.

Contact Us
 (888) 268 - 7778 x 2
joel@southendcapital.com


Tuesday, November 15, 2016

SBA Loan Scenario - Mixed Use Property Qualifies for SBA Loan


Who:

1.            Borrower owns and manages banquet   facility
2.
            Borrower has owned this business for five years
3.
            Borrower business income meets all loan requirements
4.
            Borrower has middle credit score of 635

Property Type:

1.            Mixed Use – Residential & Retail
2.
            Three apartments on the 2nd Floor               
               Business on the 1st Floor               
               Basement is finished and used by the Business
3.
            FMV       $2,200,000          MTG      $1,600,000

What:
1.            Note of current lender is now due for pay off
2.
            Borrower wants conventional rates and terms

Where: Memphis, TN

When:   Standard SBA Loan closing time is 45 – 60 days

How:    

1.            Borrower has exhausted his conventional and non-conforming loan options
2.
            Lenders had issues with:               
               a)   Open floor plan of the first floor               
               b)   Location of the property               
               c)   Credit scores of the Borrower

Decision:  Eligible for SBA Loan

Why:

1.            SBA Lender has no minimum credit score requirements 
2.            Business had required net cash flow
3.
            SBA Lender underwrote the loan based on the business nature of the property   
               and qualifying appraisal
4.
            SBA Loan requirement is the business must use 51% of the building’s square footage               
Eligibility Cure:

1.            Use of the basement added the necessary square footage to business usage for the    
               51% square footage requirement to be met

              
               Call or email Joel Soforenko and go over your Loan Scenario               
               888-268-7778 x 2 or joel@southendcapital.com

Thursday, November 10, 2016

SBA Loan Scenario – Credit Card Issue (Borrower as Co-Signor Owes Debt)


Who:

1.            Borrower wants to refinance his business debt
2.
            Borrower went through a divorce to a trial
3.
            Borrower and Ex-Spouse were ordered to split the credit card debt                and were responsible for paying off their portion of the debt
4.
            Borrower’s Ex-Spouse did not pay off the court ordered debt
5.
            This debt is found on the Borrower’s Credit Report as a charge off
What:

1.            Borrower cannot obtain an SBA Loan until this credit issue is dealt with.
2.
            Bills to be paid off total $25,000

Where: Milwaukee, WI

When:   As soon as this issue is resolved, the loan can close

How:    

1.            Borrower went through all his options including friends, relatives,                reviewing personal and business assets
2.
            Borrower could not find the means to pay off the subject debt

Decision:  Not Eligible for SBA Loan

Why:

1.            Recent charge off which could go to judgment. 
2.            FICO Score was not the issue
Eligibility Cure:

1.            The Lender of choice was apprised of the situation and cured the issue                by including the $25,000 as working capital

2.            The Borrower was allowed to use the working capital to pay off the charged off                debt at the closing. 


Call or email Joel Soforenko and go over your Loan Scenario
888-268-7778 x 2 or joel@southendcapital.com


Wednesday, November 9, 2016

Loan Scenario - Purchase Bar & Grill


Who:

1.            Borrower has dreamed of owning a tavern
2.
            Borrower is a bank branch manager
3.
            Borrower has experience as a tavern chef
4.
            Borrower rents a residence and has $125,000 in a bank account
5.
            Borrower has very good credit

What:

1.            Tavern went out of business
2.
            Tavern leased its location
3.
            All assets of the business are for sale and taking over the lease
4.
            Purchase price of assets is $400,000 dollars with an additional cost of $70,000                dollars for all other parts of the transaction.  Total $470,000.

Where: Dallas, TX

When:   Needs 60 day closing

How:    

1.            Borrower needs loan to include purchase of assets, purchase of liquor license and                renovation of the interior of the premises
2.
            Borrower has negotiated the purchase price of the Seller’s assets
3.
            Borrower will work with municipality to obtain the liquor license
4.
            Borrower needs to research the cost of renovation

Decision:  Not Eligible for SBA Loan

Why:

1.            Borrower does not have required experience as a manager or owner in the                industry.
2.
            Borrower does not have transferable skills any other transferable skills to                own a tavern
Eligibility Cure:

1.            Borrower can find a partner with the requisite experience.
2.
            Partner will need to have a minimum of 5% ownership of the new company
3.
            However, SBA Lender, Countrywide Standards is this Partner will have to fully                guarantee the loan. 


Call or email Joel Soforenko and go over your Loan Scenario
888-268-7778 x 2 or joel@southendcapital.com

Thursday, January 21, 2016

SBA Q & A : Borrower with No Experience

Background of Question:

If the primary borrower doesn’t have enough experience in the business he wants to purchase, and has to bring in a partner who will have at least a five percent (5%) ownership interest (minimum allowed for a partner with the experience to meet this requirement.

Question:

Does the five percent (5%) owner need to sign as a 100% guarantor (where the primary borrower does not have sufficient experience?

Answer:

Yes, the lender will require the person who has direct industry experience to be  one hundred percent (100%)  guarantor of the loan

Friday, October 30, 2015

SBA Loans for Unbankable Borrowers


We provide bankable SBA rates for un-bankable business owners

Question: What do a 2 year old bankruptcy, a negative 2013 NOI and an un-flagged exterior corridor hotel have in common?

Answer: $2,875,000, a 4.75% rate and a 25 year amortization!

These are the terms we funded for the business owner with the above scenario.

Contact us (888) 268-7778 x 2 or joel@southendcapital.com 

Brokers Welcome and Rebates Paid!


SBA 7(a)

$250K - $5MM

Rates start at 4.50%, no real estate is required. LTVs to 100% and credit down to 580 considered.  


Private Business

$2K - $2MM

Rates start at 6%, no real estate is required. 2-7 day closings and credit down to 500 considered. 


Stated Real Estate

$100K - $5MM

Rates start at 7.99%, no tax returns required. 2-3 week closings and credit down to 580 considered. 
  • Nationwide
  • Most industries
  • Flexible guidelines

  • US and Canada!
  • Most industries
  • Unrestricted cash


  • Nationwide
  • Most properties
  • Unrestricted cash


Sunday, September 21, 2014

Increased Loan Amounts To $5M on Non-Conforming Commercial Loans

South End Capital Increases Loan Limits to $5M; Expands Guidelines to Satisfy Market Demand

Small-balance non-conforming program now open to larger loan sizes and additional property types, at lower rates.

The response to our small private-money program has been so tremendous, we’ve boosted loan limits to $5 million, added eligible property types and lowered our rates.                  
 
South End Capital Corporation (SECC) has announced today that its highly successful small private-money program, launched this past April, will now assist borrowers seeking commercial real estate loans of $50,000 all the way up to $5,000,000—no longer limiting commercial real estate borrowers to loans under a half-million. (The SECC program is also known as the small non-conforming program.) As always, the funding is designed to accommodate borrowers with imperfect credit who are self-employed or seeking a swift and painless loan process.


According to SECC founder and Managing Director Noah Grayson, the firm will not only continue to offer private-money financing for hard-to-secure small loan sizes—and now, larger loans up to $5,000,000—but will provide financing for more property types and at improved rates. He stated, “The response to our private-money program has been so tremendous that we are now able to lower our rates to provide improved bankable pricing for ‘unbankable’ borrowers.”


Importantly, SECC can now consider single-family homes and two- to four-family apartment buildings, provided their use is for business or investment purposes. In addition, the firm can also review LTV (loan-to-value) requests up to 75 percent.


Added Grayson, “Borrowers will also be surprised to discover that, unlike conventional lenders, we can now underwrite many loan transactions based on stated information and verification of property information only—often no tax returns are required.”


SECC’s newly expanded nationwide private-money loan program has no borrower credit score minimum and no population restrictions; primary, secondary and tertiary markets are generally allowed. Most commercial property types qualify and rates start as low as 6.5% percent with no or low loan points. Loan closings can take place in as few as two to three weeks. Additional program criteria are available right now.


SECC welcomes both borrower and broker inquiries. The firm also offers referral fees to approved partners. To inquire about this program or any of the many innovative programs available through South End Capital Corp., contact Joel Soforenko directly at (888) 268.7778 ext. 2, or joel@southendcapital.com